
A high-yield savings account can help keep emergency funds liquid, relatively safe, and capable of earning more interest than traditional savings accounts. The appropriate fund size depends on essential expenses, income stability, responsibilities, and financial risks.
When comparing accounts, consider APY stability, fees, access, transfer times, withdrawal rules, promotional conditions, and FDIC insurance rather than focusing only on the highest advertised rate. The guide also outlines ways to build, automate, layer, and replenish an emergency fund.
An emergency fund is supposed to be boring.
You want the money available when you need it, protected from market swings, and earning something while it sits there. You don’t want to chase risky investments with it, lock it away for years, or discover that accessing it in an emergency comes with unnecessary fees.
That’s where a high-yield savings account (HYSA) can fit into the picture.
A HYSA works much like a traditional savings account, but it can offer a substantially higher annual percentage yield (APY). For someone building or maintaining an emergency fund, that combination of liquidity, relatively low risk, and interest income can make it worth considering.
But the highest advertised rate isn’t necessarily the most important factor.
A good emergency-fund account should balance yield, access, fees, safety, and simplicity.
Key Takeaways
- An emergency fund should prioritise accessibility and stability rather than maximum investment returns.
- A HYSA can allow emergency savings to earn more interest without putting the money into the stock market.
- APYs can change, so today’s highest rate may not remain the highest rate for long.
- Check fees, minimum balances, withdrawal rules, transfer times, and account conditions before opening an account.
- In the U.S., deposits at an FDIC-insured bank are generally insured up to $250,000 per depositor, per insured bank, for each ownership category.
- The best emergency-fund strategy is usually the one you can maintain consistently—not necessarily the one with the highest advertised APY.
What Is a High-Yield Savings Account?
A high-yield savings account is a deposit account designed to pay a higher interest rate than many traditional savings accounts.
The basic idea is simple:
Your money stays in a savings account, but the account pays a more competitive APY.
Unlike stocks, mutual funds, or other market investments, the balance in a savings account isn’t directly exposed to daily market price movements.
That makes the account potentially useful for money that needs to remain readily available.
However, “high-yield” isn’t a permanent label. Banks can change savings rates, and the APY you see when opening an account can be different later.
Interest rates across deposit accounts are influenced by the broader interest-rate environment. For example, the Federal Reserve raised its target federal funds rate to a range of 3.75%–4.00% in September 2026.
That matters because savings-account rates can move as the interest-rate environment changes.
Why Put an Emergency Fund in a HYSA?
An emergency fund has a different job from a long-term investment portfolio.
Its purpose is to help you handle unexpected expenses without having to sell investments at an inconvenient time or rely on expensive borrowing.
The Consumer Financial Protection Bureau describes an emergency fund as money specifically set aside for unplanned expenses and financial emergencies.
Common examples include:
- An unexpected medical bill
- A sudden loss of income
- An urgent home repair
- A major car repair
- An essential family expense
- An unexpected travel expense
Because the money may be needed without much warning, liquidity matters.
A HYSA can therefore provide a middle ground:
More interest than a basic savings account + easier access than many longer-term savings products.
How Much Should You Keep in an Emergency Fund?
There is no universal number.
The familiar recommendation is three to six months of essential expenses, but your actual target should reflect your circumstances.
For example:
| Essential Monthly Expenses | 3 Months | 6 Months |
|---|---|---|
| $2,000 | $6,000 | $12,000 |
| $3,000 | $9,000 | $18,000 |
| $4,000 | $12,000 | $24,000 |
| $5,000 | $15,000 | $30,000 |
Someone with highly predictable employment and relatively low financial obligations may be comfortable with a smaller reserve.
Someone with variable income, dependents, or less predictable expenses may prefer a larger cushion.
The important point is that you should calculate the fund from essential expenses, not simply from your salary.
A Simple Formula
Emergency Fund Target = Essential Monthly Expenses × Number of Months
Suppose your essential expenses are $3,500 per month.
A six-month target would be:
$3,500 × 6 = $21,000
That $21,000 becomes the target for your emergency reserve.
You can use a smaller initial target if building the full amount feels overwhelming. The important thing is to establish the habit and increase the balance over time.
How Much Can a HYSA Earn?
This is where the difference between a regular savings account and a higher-yield account can become noticeable.
Consider a hypothetical $20,000 emergency fund.
At a 0.50% annual rate, the simple one-year interest would be approximately:
$20,000 × 0.005 = $100
At a hypothetical 4.00% APY, the annual interest would be approximately:
$20,000 × 0.04 = $800
The difference is substantial.
But these are illustrations, not guaranteed returns. Actual earnings depend on the account’s APY, balance, compounding, and how long the money remains deposited.
More importantly, don’t choose an emergency account simply because it currently has the highest rate.
A bank offering a slightly lower rate with no monthly fee, easy transfers, and straightforward terms may be more useful than an account offering a headline rate with restrictions.
What Should You Look for in a HYSA?
Before moving your emergency fund, compare the account’s full terms rather than looking at APY alone.
1. APY
The annual percentage yield tells you how much interest the account can earn over a year, assuming the stated conditions are met.
Look for:
- Current APY
- Whether the rate is promotional
- Whether the rate applies to the entire balance
- Whether there are balance tiers
- Whether the bank can change the rate
Savings rates are generally variable, so don’t assume today’s rate will remain unchanged.
2. Fees
Fees can quietly reduce the benefit of a higher interest rate.
Check for:
- Monthly maintenance fees
- Excess withdrawal fees
- Transfer fees
- Minimum-balance requirements
- Other account-specific charges
The CFPB notes that financial institutions can impose fees for certain savings-account transactions and may set limits on withdrawals or transfers.
A no-fee account can therefore be particularly attractive for an emergency fund.
3. Access to Your Money
Emergency money isn’t useful if accessing it takes too long.
Check:
- How you transfer money out
- Whether transfers are free
- Typical transfer times
- Whether you can link an external checking account
- Whether there are withdrawal or transfer restrictions
- Whether the account provides ATM access, if that matters to you
You don’t necessarily need instant cash access for every dollar of your emergency fund, but you should understand exactly how the money becomes available.
4. Deposit Insurance
For U.S. savers, confirm that the bank is FDIC-insured.
The standard FDIC coverage limit is $250,000 per depositor, per insured bank, for each account ownership category.
That insurance is fundamentally different from investment performance protection. It is designed to protect eligible deposits if an insured bank fails, subject to the applicable coverage rules.
Don’t assume every financial product labelled as a “cash” or “savings” product receives the same type of protection. Verify what you’re actually purchasing.
HYSA vs. Other Places to Keep Emergency Money
A HYSA isn’t the only possible home for emergency savings.
| Option | Liquidity | Market Risk | Potential Return | Typical Use |
|---|---|---|---|---|
| HYSA | High | Very low | Moderate | Core emergency fund |
| Traditional Savings | High | Very low | Lower | Everyday or emergency savings |
| Money Market Deposit Account | High | Very low | Moderate | Cash reserves |
| Certificate of Deposit | Lower | Very low | Moderate | Money not needed immediately |
| Stocks | High to moderate | High | Higher potential | Long-term investing |
| Bonds/Debt Funds | Varies | Varies | Varies | Depends on product and horizon |
The key distinction is that an emergency fund is not trying to maximise investment returns.
It is trying to make sure that money is there when you need it.
That means an account earning a little less can still be a sensible choice if it provides better access, fewer restrictions, or greater simplicity.
Should Your Entire Emergency Fund Be in One Account?
Not necessarily.
Some people prefer a simple one-account approach:
Emergency fund → HYSA
Others use a layered structure.
For example:
Layer 1: Immediate cash
Keep a smaller amount in a checking or savings account that is extremely easy to access.
Layer 2: Core emergency fund
Keep the majority in a competitive HYSA.
Layer 3: Longer-duration reserves
If you have a larger emergency reserve and understand the trade-offs, you might consider other conservative savings vehicles for money that is less likely to be needed immediately.
The exact structure depends on your circumstances.
The important principle is to avoid putting money you might need tomorrow into something that makes accessing it difficult.
Don’t Chase Every Rate Change
One of the easiest mistakes to make is constantly moving your money whenever another bank advertises a slightly higher APY.
Suppose Account A pays 3.90% and Account B pays 4.00%.
On a $10,000 balance, the difference in simple annual interest is only about:
$10 per year.
If moving the money requires extra paperwork, creates transfer delays, introduces account-management complexity, or makes you more likely to abandon the emergency-fund system altogether, the tiny rate difference may not justify the effort.
Instead, review your account periodically and move only when the overall improvement is meaningful.
Watch Out for Promotional Rates
A rate that looks unusually high may come with conditions.
For example, an account might require:
- A minimum balance
- Direct deposit
- A certain number of transactions
- New-customer eligibility
- A promotional period
Always check what happens after the promotion ends.
The relevant question isn’t:
“What’s the highest rate advertised?”
It’s:
“What rate and account conditions will apply to my money under normal circumstances?”
What Not to Do With Your Emergency Fund
An emergency fund should not become an extension of your investment portfolio.
Avoid treating it as money for:
- Stock-market speculation
- Cryptocurrency purchases
- A vacation
- A new gadget
- A planned shopping spree
- An investment opportunity you suddenly want to take
The fund exists for unexpected needs.
If you regularly withdraw it for planned purchases, consider creating separate sinking funds for those goals.
For example:
Emergency fund: Unexpected medical or household expense
Car fund: Planned maintenance and repairs
Travel fund: Vacation
Home fund: Planned improvements
Keeping these purposes separate makes it easier to know when an expense genuinely qualifies as an emergency.
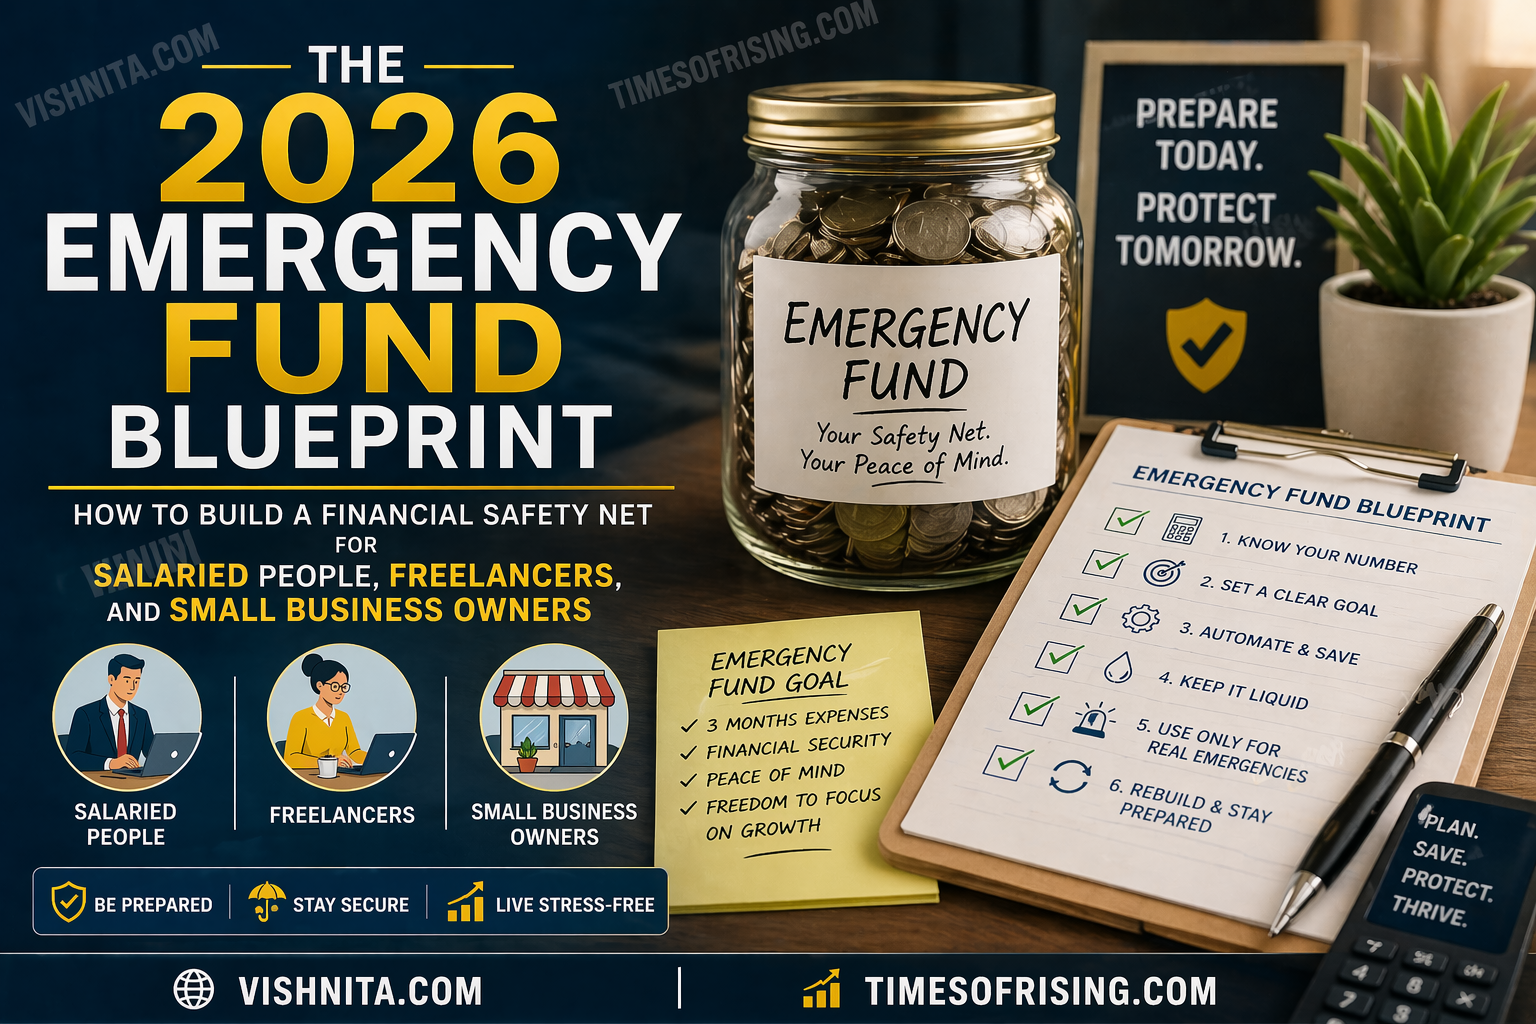
A Practical Way to Build Your HYSA Emergency Fund
If you’re starting from zero, don’t wait until you can save several months of expenses.
Use milestones.
Step 1: Calculate Your Essential Expenses
Review your recent spending and identify the bills you would still need to pay during a financial setback.
Include essentials such as:
- Housing
- Utilities
- Groceries
- Insurance
- Transportation
- Minimum debt payments
- Essential healthcare costs
Step 2: Set an Initial Target
Start with a realistic first milestone.
It could be $500, $1,000, or another amount appropriate for your situation.
The first goal is to establish a financial buffer.
Step 3: Build Toward One Month
Once your starter fund is established, work toward one month of essential expenses.
Step 4: Increase to Three Months
Continue automated contributions until you have roughly three months of essential expenses.
Step 5: Decide Whether Six Months Makes Sense
Evaluate your income stability, household responsibilities, insurance coverage, and other financial risks.
If your circumstances justify a larger reserve, continue building.
Step 6: Automate Contributions
Automation removes one decision from your monthly routine.
Set up an automatic transfer shortly after receiving income rather than waiting to see what remains at the end of the month.
Even a modest recurring contribution can gradually turn into a meaningful reserve.
What Happens When You Use the Emergency Fund?
Using an emergency fund doesn’t mean you failed.
That’s what the fund is there for.
The important step is what happens afterwards.
Suppose you have $18,000 saved and need $4,000 for an unexpected expense.
Your balance falls to $14,000.
Once the emergency is resolved, redirect part of your normal savings toward rebuilding the $18,000 target.
Don’t simply continue investing as though the emergency fund were still fully funded.
A Simple HYSA Checklist
Before choosing an account, ask:
- What is the current APY?
- Is the rate promotional?
- Can the bank change the rate?
- Are there monthly fees?
- Is there a minimum balance?
- Are there withdrawal or transfer restrictions?
- How quickly can I access the money?
- Is the bank FDIC-insured?
- Does the account have any special requirements?
- What happens to the rate after the introductory period?
- Is the account simple enough that I will actually keep using it?
If the answers make sense, the account may be suitable for your emergency savings strategy.
The Bottom Line
An emergency fund doesn’t need to be exciting.
That’s actually the point.
You want your emergency savings to be safe, accessible, separate from everyday spending, and productive enough that your cash isn’t unnecessarily sitting idle.
A high-yield savings account can provide a useful balance between those goals. But the highest APY shouldn’t automatically determine your choice.
Focus on the complete package: rate, fees, access, insurance, restrictions, and reliability.
And remember that interest rates change. Review your account occasionally, but don’t turn your emergency fund into a constant rate-chasing exercise.
The strongest emergency fund is the one that is properly sized, easy to access, and ready when an unexpected expense arrives.
This article is for educational purposes only and is not individualised financial advice. Account rates, terms, fees, insurance coverage, and eligibility can change. Verify current terms directly with the financial institution before opening an account or moving money.

Almost there!
Your comment box is getting ready. Have a little fun while you wait.
Your comment box will appear when the timer reaches zero.